Before the Sandbags: Underwriting Flood Exposure in UK Renovation Appraisals for 2026
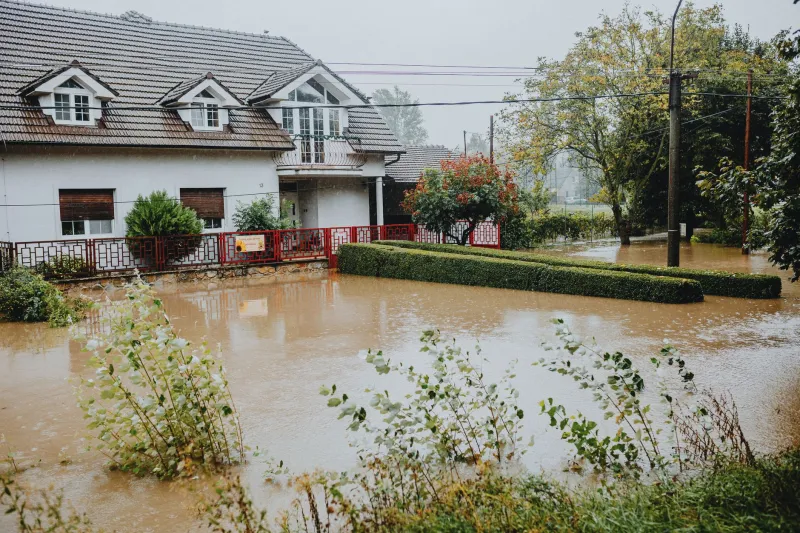
Flood risk is often treated as a planning constraint to be addressed late in the acquisition process. For UK renovation projects, that sequencing is increasingly difficult to defend. A property may be physically sound and competitively priced, yet the combination of insurance cost, lender caution and resilience expenditure can materially change the appraisal. In 2026, flood exposure should be underwritten as a financial and technical variable from the first site visit, not as a documentary afterthought.
Flood risk is a pricing variable, not a planning footnote
The relevant question is not simply whether a site appears within a flood zone. It is whether the completed scheme can be insured, mortgaged, occupied and sold on terms that justify the works. A renovation that improves the fabric of a building but leaves the asset exposed to repeated inundation may deliver a poorer exit than a less ambitious scheme on a lower-risk plot.
For that reason, flood due diligence should sit alongside structural survey, title review and planning history. It should inform the maximum bid, the contingency and the specification. Where the risk is material, it should also inform the decision not to proceed.
Map the exposure across all sources
The Environment Agency’s flood map for planning provides a useful starting point for fluvial and tidal risk, but it is not a complete assessment. Surface-water flooding is frequently the more immediate concern in dense urban areas, where impermeable surfaces and constrained drainage can produce localised pooling well away from a main river. Lead local flood authorities hold surface-water mapping and historic records; strategic flood risk assessments prepared by the local planning authority can add context.
A robust review should consider:
- fluvial and tidal zones, including climate-change allowances;
- surface-water depth and flow paths;
- groundwater vulnerability and recorded sewer flooding;
- the route and condition of drainage runs, basements and lightwells;
- access and egress during an event, not only the footprint of the building.
For terraces and conversions, the unit of assessment matters. A lower-ground flat, a cellar conversion or a rear extension may carry a different exposure from the upper floors. Appraisals that apply a single postcode-level view can miss the part of the scheme that will be hardest to insure or sell.
Test insurance and mortgageability before exchange
Specialist flood insurance quotes should be obtained before contracts are exchanged, not after planning consent. The premium is only one output; the excess, exclusions and reinstatement conditions matter as much. A policy that is affordable in a dry year may be untenable once excesses for flood damage are applied.
Flood Re eligibility should be checked rather than assumed. The scheme has improved residential availability in some circumstances, but it does not resolve every leasehold, commercial or lending scenario. Where the property is to be let, converted or sold to an owner-occupier, the insurance position should be tested against the intended occupational model.
Lenders may also apply their own flood risk appetite. A valuation that assumes standard mortgage availability can be undermined by a surveyor’s flood note or a lender’s postcode criteria. Early conversations with a broker and, where appropriate, a surveyor familiar with the locality are more useful than a late attempt to remedy a funding gap.
Price the resilience premium separately
Flood mitigation is not a single cost. It is a package whose scope should be driven by the likely depth, duration and frequency of flooding. Basic measures may include non-return valves on drainage, raised electrical services, capped sockets at a higher level, water-resistant wall finishes and sacrificial ground-floor materials. More extensive schemes may require sump and pump systems, improved drainage, tanking, or external ground-level works.
These items should appear as separate lines in the appraisal, with a clear distinction between regulatory requirements, insurer expectations and voluntary resilience. Mixing them into a general contingency obscures the true cost of the site and weakens later negotiation.
Specification also has a build-quality dimension. Water-resistant materials that are poorly detailed can trap moisture or complicate drying. Raised services are of limited value if cable routes and consumer units remain vulnerable. The objective is not to create a waterproof box, but to design a building that can be dried, inspected and reinstated without wholesale strip-out.
Keep a documented audit trail
For exit value, evidence matters. A schedule of flood mitigation measures, product data, installation records and maintenance instructions can support insurance discussions and buyer due diligence. Where works affect drainage or ground levels, completion photographs and professional sign-off are prudent.
Disclosure should be accurate and proportionate. A buyer’s lender and insurer will form their own view, and an undocumented claim of resilience is unlikely to carry weight. The same applies to warranties: a guarantee for tanking or pump equipment is only useful if it is assignable and supported by records.
Reflect the risk in the appraisal
The financial treatment should be explicit. A simple base case might assume standard insurance and no resilience spend; a risk-adjusted case should include quoted premiums, excesses, mitigation capex and a longer void or reinstatement allowance. The difference between the two cases is the flood discount the purchaser should seek.
If the discount is unavailable, the project may still be viable—but only if the completed asset can be clearly differentiated by its resilience, documentation and insurability. That is a higher evidential bar than most refurbishment appraisals currently apply.
In 2026, flood risk is best understood as a component of build quality and investment performance. Mapping it early, pricing it honestly and specifying for recovery rather than mere resistance gives UK developers a more defensible route from acquisition to exit.